


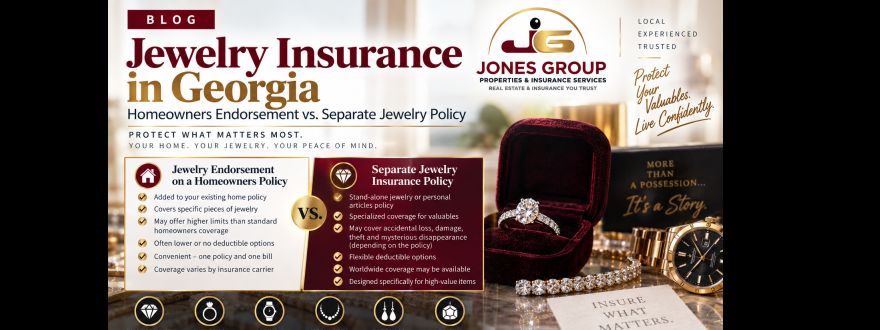
Jewelry Endorsement on a Homeowners Policy vs. a Separate Jewelry Insurance Policy
Your engagement ring, wedding ring, diamond earrings, luxury watch or family heirloom may be some of the smallest items you own—but also some of the most valuable.
Many homeowners assume:
“I have homeowners insurance, so my jewelry is already fully covered.”
That isn't necessarily the case.
A homeowners policy may provide some coverage for jewelry, but policies can contain special limits for certain types of losses involving jewelry and other valuable property.
If you own valuable jewelry, you may have two options worth discussing with your insurance agent:
1. Schedule or endorse the jewelry onto your homeowners policy
or
2. Purchase a separate jewelry or personal articles policy
At Jones Group Properties & Insurance Services, we help clients throughout Marietta, Acworth, Kennesaw, Woodstock, Canton, Smyrna, East Cobb, Cobb County, Paulding County, Dallas, Hiram and surrounding Georgia communities understand their options for protecting valuable personal property.
Doesn't My Homeowners Insurance Already Cover My Jewelry?
Your homeowners policy generally includes personal property coverage.
However, that doesn't automatically mean an expensive piece of jewelry is protected for its full value under every type of loss.
Homeowners policies may contain special limits of liability for jewelry, watches, precious stones and similar valuable items, particularly for certain causes of loss such as theft.
The specific limit depends on your insurance carrier and policy form.
For example, imagine you own:
$12,000 engagement ring
$7,500 diamond bracelet
$5,000 luxury watch
That's $24,500 in jewelry.
You should not assume your homeowners policy would automatically pay $24,500 if all three items were stolen.
This is why valuable jewelry should be discussed separately with your insurance agent.
Option 1: Adding a Jewelry Endorsement to Your Homeowners Policy
One common option is to schedule the jewelry onto your homeowners policy.
You may hear this described as:
Scheduled Personal Property
Scheduled Jewelry
Personal Articles Endorsement
or a similar term depending on the insurance carrier.
Instead of relying only on the standard personal-property provisions of the homeowners policy, specific pieces of jewelry can be individually identified and insured.
For example:
Diamond Engagement Ring – $15,000
Wedding Band – $5,000
Diamond Earrings – $7,500
The insurer may require documentation supporting the value before scheduling the items.
What Are the Advantages of Scheduling Jewelry on Your Home Policy?
For many homeowners, this can be a convenient option.
Everything Is With One Insurance Company
Your home and scheduled jewelry can remain together under the same insurance program.
That can make billing and policy administration easier.
Broader Coverage May Be Available
Scheduled jewelry coverage may provide protection beyond what the standard homeowners policy provides.
Depending upon the policy, this can include certain types of accidental loss.
Higher Limits
Scheduling an expensive piece individually allows the policy to specifically identify the item and its insured value rather than relying solely on the homeowners policy's general jewelry limitations.
Different Deductible Options May Be Available
Some scheduled-property endorsements may have a lower deductible—or potentially no deductible—for covered jewelry losses.
This varies by insurance carrier, so always verify the actual deductible shown on the policy.
What Is a Separate Jewelry Insurance Policy?
The second option is to insure the jewelry under a separate policy specifically designed for valuable personal articles.
Depending on the insurance company, this may be called:
Jewelry Insurance
Personal Articles Policy
Personal Articles Floater
Inland Marine Policy
or another product name.
Instead of attaching the jewelry coverage to your homeowners insurance, the jewelry has its own policy.
Why Would Someone Choose a Separate Jewelry Policy?
There are several reasons a homeowner might prefer this approach.
The Jewelry Isn't Tied to the Homeowners Policy
The jewelry coverage exists separately from the home policy.
This can be useful for clients who own particularly valuable collections or want specialized coverage.
Specialized Jewelry Coverage
A standalone jewelry insurer may offer coverage designed specifically around jewelry risks.
Depending on the policy, this could include qualifying losses involving theft, accidental damage, disappearance or loss.
Different Deductible Choices
A standalone jewelry policy may offer deductible options that differ from the homeowners policy.
Specialized Claims Handling
Some specialty insurers focus specifically on jewelry and valuable articles and may have claims processes designed around repairing or replacing jewelry.
Again, the exact benefits depend on the policy and carrier.
What About Losing Your Ring?
This is one of the most important questions to ask.
Imagine you look down one afternoon and realize:
Your diamond is gone.
You don't know exactly when or where you lost it.
That's different from someone breaking into your home and stealing it.
A standard homeowners policy may not treat simple loss or mysterious disappearance the same way it treats a covered theft.
Properly scheduled jewelry or a specialized jewelry policy may offer broader protection for certain accidental-loss situations, depending on the policy.
Example
You have a $15,000 engagement ring.
You go on vacation and later realize the ring is missing.
You don't know whether it fell off at the hotel, restaurant or airport.
If your coverage includes this type of loss, your scheduled jewelry or standalone jewelry policy may respond subject to the policy terms.
Without appropriate coverage, you could potentially be responsible for replacing the ring yourself.
What If the Diamond Falls Out of the Setting?
Here's another scenario homeowners sometimes overlook.
The ring itself isn't stolen.
Instead, one of the prongs breaks and the diamond falls out.
Whether that loss is covered depends on the policy.
This is exactly why valuable jewelry owners should look beyond simply asking:
“Is my ring insured?”
A better question is:
“What types of losses does my jewelry coverage actually insure?”
Jewelry Endorsement vs. Separate Jewelry Policy
Here's a simple comparison for your clients:
FeatureHomeowners Jewelry EndorsementSeparate Jewelry PolicyPolicyAttached to home policySeparate policyJewelry individually scheduledOftenOftenAppraisal may be requiredPossiblyPossiblyHigher jewelry limitsYes, subject to policyYes, subject to policyAccidental lossMay be availableMay be availableMysterious disappearanceMay be availableMay be availableDeductibleVaries by carrierVaries by carrierClaimsThrough homeowners carrierThrough jewelry insurerSpecialized jewelry programCarrier dependentOftenConvenienceOne home insurance programSeparate policy/billing
Neither option is automatically better for everyone.
The right choice depends on the value of the jewelry, available carrier coverage, deductible, premium and the client's preferences.
Will a Jewelry Claim Affect My Homeowners Insurance?
This is another reason some clients ask about a separate jewelry policy.
If jewelry is scheduled directly on the homeowners policy, a covered jewelry claim is generally handled within that insurance arrangement.
With a standalone jewelry policy, the claim is handled under the separate jewelry policy.
However, don't assume that having a separate jewelry policy guarantees a claim can never affect future homeowners underwriting. Insurance companies have different underwriting rules and may consider prior loss history differently.
If this issue is important to you, discuss it with your insurance agent before choosing the policy.
How Much Should I Insure My Jewelry For?
Jewelry values can change over time.
Gold, diamonds, precious stones, designer pieces and collectible watches may increase or decrease in value.
For higher-value items, an insurance company may request documentation such as:
-
Recent appraisal
-
Purchase receipt
-
Detailed item description
-
Photographs
-
Diamond grading report
-
Serial number for certain watches
-
Documentation of gemstone characteristics
The carrier will determine exactly what documentation is required.
How Often Should Jewelry Be Appraised?
If an appraisal is several years old, it may no longer accurately represent the cost of replacing the item.
Consider periodically reviewing valuable jewelry with your jeweler and insurance agent.
The goal isn't simply to increase coverage every year.
It's to make sure your scheduled limit reasonably reflects the amount needed under the policy's valuation method.
Engagement Ring Insurance in Georgia
An engagement ring is often the first piece of jewelry a client specifically asks us to insure.
If you've recently purchased or received an engagement ring, don't wait until after the wedding to review the insurance.
Ask your insurance agent about coverage as soon as you take possession of the ring.
You'll typically want to know:
How much is it insured for?
Is there a deductible?
Is theft covered?
Is accidental loss covered?
What about mysterious disappearance?
What happens if only the stone is lost?
Does the insurer repair, replace or pay cash?
These questions are much more useful than simply asking whether the ring is “covered.”
What About Watches, Diamonds and Other Valuable Items?
Jewelry insurance isn't limited to wedding rings.
Depending upon the insurer, coverage may be available for items such as:
Diamond jewelry | Necklaces | Bracelets | Earrings | Luxury watches | Gemstones | Family heirlooms
Other categories of valuable property—such as fine art, collectibles, firearms, silverware or musical instruments—may have their own coverage requirements and shouldn't automatically be treated as jewelry.
Jewelry Insurance in Marietta, GA
Jones Group Properties & Insurance Services helps homeowners throughout Marietta evaluate insurance for valuable jewelry and personal property.
Whether you're purchasing a new engagement ring or reviewing jewelry you've owned for years, we can help you determine whether scheduling it on your homeowners policy or considering separate coverage makes sense.
Jewelry Insurance in Acworth & Kennesaw, GA
We also assist homeowners throughout Acworth and Kennesaw with homeowners insurance and valuable-property coverage.
If you've recently purchased expensive jewelry, don't assume your existing homeowners limits automatically provide the protection you expect.
Contact us so we can review the available options.
Jewelry Insurance in Woodstock & Canton, GA
Homeowners throughout Woodstock, Canton and Cherokee County can also contact Jones Group for assistance protecting valuable jewelry.
A quick insurance review can help determine whether your current homeowners policy provides adequate protection or whether scheduled or separate coverage should be considered.
Jewelry Insurance in Smyrna & East Cobb, GA
We also serve clients throughout Smyrna and East Cobb.
Higher-value homes often contain valuable personal property that deserves a separate review.
Jewelry is only one example.
When reviewing homeowners insurance, it's worth discussing any high-value items with your insurance agent instead of assuming the standard personal-property limit addresses everything.
Jewelry Insurance in Cobb County, Georgia
Jones Group serves homeowners throughout Cobb County, including:
Marietta | Acworth | Kennesaw | Smyrna | East Cobb and surrounding communities.
If you're reviewing your homeowners insurance, this is an excellent time to review jewelry, valuables and other special property limits as well.
Jewelry Insurance in Paulding County, Dallas & Hiram
We also assist homeowners throughout Paulding County, including Dallas and Hiram.
Whether you're buying a new home, recently purchased valuable jewelry or simply haven't reviewed your insurance in several years, we can help evaluate your available coverage options.
Which Is Better: A Homeowners Jewelry Endorsement or Separate Jewelry Policy?
There isn't one answer for every client.
For someone with one or two moderately valued pieces, scheduling the jewelry on the homeowners policy may be convenient and cost-effective.
For someone with a substantial jewelry collection, very expensive pieces or who wants a specialized jewelry-insurance program, a standalone policy may deserve consideration.
The key is comparing more than price.
Ask about:
Covered causes of loss | Deductible | Valuation | Repair or replacement provisions | Worldwide coverage | Appraisal requirements | Newly acquired jewelry | Coverage limits | Exclusions
Then make the decision based on the actual coverage.
Get a Jewelry Insurance Quote in Georgia
Your jewelry may represent much more than its dollar value.
Wedding rings, anniversary gifts and family heirlooms often carry memories that can't be replaced.
While insurance can't replace the sentimental value, having appropriate coverage can help protect the financial investment.
Jones Group Properties & Insurance Services can help you compare options for scheduling jewelry on your homeowners policy or obtaining separate jewelry coverage.
We serve:
Marietta | Acworth | Kennesaw | Woodstock | Canton | Smyrna | East Cobb | Cobb County | Paulding County | Dallas | Hiram | and surrounding Georgia communities.
Jones Group Properties & Insurance Services
Real Estate & Insurance You Trust
Protect your home. Protect your valuables. Protect what matters.
Request Your Jewelry Insurance Quote Today.