


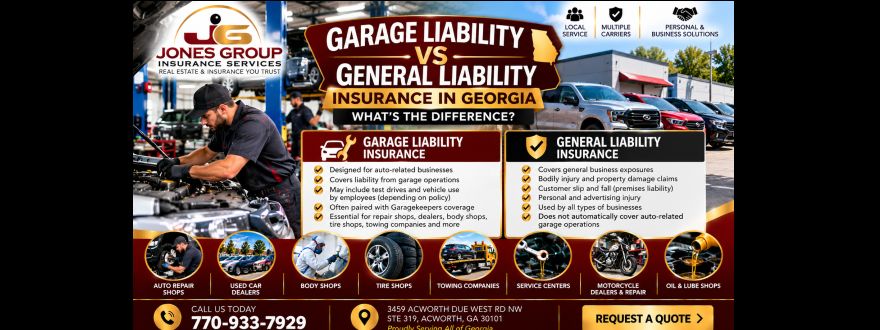
Garage Liability vs. General Liability Insurance: What Georgia Auto Businesses Need to Know
If you own an auto repair shop, used car dealership, body shop, tire shop, towing company, or another automotive business in Georgia, you may have heard the terms General Liability Insurance and Garage Liability Insurance.
But are they the same thing?
No. General Liability and Garage Liability are designed for different types of business exposures.
Understanding the difference is especially important for businesses that sell, service, repair, park, tow, or otherwise work around vehicles.
At Jones Group Insurance Services, we help Georgia business owners understand which commercial insurance coverages may be appropriate for their specific operations.
What Is General Liability Insurance?
Commercial General Liability Insurance, commonly called CGL or General Liability, is designed to protect businesses against certain third-party claims involving bodily injury, property damage, and personal or advertising injury, subject to the policy's terms, conditions and exclusions.
General liability is used across many different industries.
For example, imagine a customer visits your business and slips and falls in your office.
The customer suffers an injury and alleges that your business was negligent.
That is the type of premises liability exposure that may fall under a General Liability policy.
General Liability may also address certain claims involving property damage caused by your business operations.
However, an automotive business has exposures that an ordinary office, retail store, or contractor may not have.
That's where Garage Liability Insurance becomes important.
What Is Garage Liability Insurance?
Garage Liability Insurance is specifically designed for businesses involved in garage operations and automotive-related activities.
Depending on the carrier and policy form, this may include businesses such as:
- Auto repair shops
- Used car dealerships
- Body shops
- Tire shops
- Oil and lube shops
- Auto service centers
- Towing operations
- Motorcycle dealers or repair operations
- Other automotive businesses
Garage liability can address liability exposures arising from the operation of an automotive business, subject to the specific policy.
For example, suppose an employee of an auto repair shop takes a customer's vehicle for a test drive after completing repairs and causes an accident.
That creates a very different exposure from a customer simply slipping and falling in the shop's waiting room.
An automotive business needs insurance designed to contemplate its garage operations and automobile liability exposures.
Garage Liability vs. General Liability: What's the Main Difference?
The easiest way to understand the difference is to look at what each policy is designed around.
General Liability is designed for the general liability exposures businesses face, such as certain premises and operations claims involving bodily injury or property damage.
Garage Liability is designed specifically around businesses engaged in garage or automotive operations and can include liability exposures associated with those operations.
An auto business shouldn't assume that purchasing a standard General Liability policy gives it the same protection as a properly written Garage Liability policy.
Likewise, simply having Garage Liability does not mean every possible exposure associated with your business is automatically covered.
The policy form matters.
What Happens When Employees Drive Vehicles?
This is one of the most important reasons automotive businesses need to disclose their full operations.
Imagine you own a repair shop in Georgia.
A customer brings in a vehicle for repairs. After completing the work, your mechanic takes the vehicle onto the road for a test drive.
During the test drive, your employee causes an accident and another driver is injured.
A traditional General Liability policy may not be designed to address that automobile exposure.
A properly structured garage insurance program can include liability protection associated with covered garage operations and vehicle use.
This is why your insurance agent needs to know whether your employees:
test-drive vehicles, pick up customer vehicles, deliver vehicles, drive dealership inventory, tow vehicles, transport vehicles, or perform other automobile-related activities.
What About a Customer's Vehicle While It's in Your Shop?
Here's another important distinction.
Garage Liability should not be confused with Garagekeepers Insurance.
Suppose a customer's vehicle is sitting inside your repair facility overnight and is damaged by a covered cause of loss.
Or a mechanic accidentally damages the customer's vehicle while it is in the shop's care.
The customer's automobile is property in your business's care, custody or control.
That is where Garagekeepers coverage may become important.
Garage Liability and Garagekeepers are not the same coverage.
A business may need both.
Garage Liability vs. Garagekeepers Insurance
A simple way to remember the difference is:
Garage Liability = Liability arising from your garage operations.
Garagekeepers = Protection involving customers' vehicles left in your care, custody or control, subject to the coverage selected and policy terms.
For example:
Your mechanic test-drives a customer's vehicle and causes an accident involving another motorist. That could create a Garage Liability/auto liability exposure.
Your customer's vehicle is damaged while being kept at your shop. That could create a Garagekeepers exposure.
These are different situations and may require different coverages.
What About Tow Trucks and Vehicles Being Towed?
Towing businesses present another specialized exposure.
If you operate tow trucks, Garage Liability or commercial auto coverage alone should not automatically be assumed to cover damage to the vehicle you're towing.
A towing operation may need On-Hook Towing coverage for customers' vehicles while they are being towed.
Businesses transporting vehicles rather than performing traditional towing may also need to discuss Motor Truck Cargo coverage.
That's why it's important to tell your agent exactly what your business does instead of simply asking for "tow truck insurance."
What Insurance Does an Auto Repair Shop Need?
An auto repair shop's insurance program may include several different policies or coverages depending on its operations.
For example, a shop could potentially need Garage Liability, Garagekeepers, Commercial Property, Workers' Compensation, Commercial Umbrella, Employment Practices Liability, Cyber Liability, and other coverages.
If the business owns tow trucks or other vehicles, Commercial Auto and On-Hook coverage may also need to be considered.
There is no single insurance package that's appropriate for every garage business.
What Insurance Does a Used Car Dealer Need?
Used car dealerships can have another set of exposures.
A dealership may have customers test-driving vehicles, employees moving inventory, vehicles parked on a sales lot, dealer plates, customers entering the premises and employees driving vehicles.
Depending on the operation, coverage may include Garage Liability, dealer auto coverage, physical damage for inventory, Garagekeepers, property coverage, Workers' Compensation, Umbrella Liability, and other insurance.
The number of vehicles, maximum inventory value, dealer plates, drivers and business operations can all affect underwriting.
Why Buying Only General Liability Can Be a Problem for an Auto Business
One of the biggest mistakes an automotive business owner can make is requesting:
"I just need a $1 million General Liability policy."
That may sound straightforward, but your actual operations matter more than the name of the coverage requested.
If you're repairing, servicing, selling, towing, storing or test-driving vehicles, make sure your insurance agent knows.
A cheaper General Liability policy is not necessarily a substitute for insurance specifically designed for garage operations.
Your agent should understand your business before recommending coverage.
Information You Should Give Your Insurance Agent
When requesting a garage insurance quote, be prepared to provide information about your business operations, annual revenue, payroll, number of employees, drivers, years in business, services performed, vehicle inventory, customer vehicles, test drives, towing operations, building and equipment, prior claims and desired limits.
The more accurately your operation is described, the better your agent can identify the appropriate insurance markets.
And don't leave out an operation because you think it isn't important.
Something as simple as employees occasionally test-driving customer vehicles can be very important to underwriting.
Garage Liability Insurance in Georgia
Jones Group Insurance Services helps automotive businesses find commercial insurance options throughout Atlanta, Marietta, Acworth, Kennesaw, Woodstock, Canton, Smyrna, East Cobb, Cobb County, Paulding County, and throughout Georgia.
We work with businesses including auto repair shops, used car dealerships, body shops, tire shops, towing companies and other automotive operations.
Whether you're opening a new business or reviewing an existing policy, we'll take the time to understand what your company actually does before exploring insurance options.
Get a Garage Liability Insurance Quote in Georgia
If you own an automotive business, don't assume that General Liability alone provides all the coverage your operation needs.
Contact Jones Group Insurance Services to discuss your business and request a Garage Liability insurance quote.
Jones Group Insurance Services
3459 Acworth Due West Rd NW, Suite 319
Acworth, GA 30101
770-933-7929
Serving Atlanta, Marietta, Acworth, Kennesaw, Woodstock, Canton, Smyrna, East Cobb, Cobb County, Paulding County, and businesses throughout Georgia.